Managing household finances in the modern era presents challenges that previous generations never had to navigate. The transition to cashless transactions, digital banking, subscription-based services, and algorithmic consumer marketing has made spending money nearly frictionless. At the same time, shifting economic dynamics, rising living costs, and evolving career patterns require families to manage their personal balance sheets with high precision.
Financial literacy is no longer just about balancing a checkbook or stashing dollar bills in an envelope. For modern families, it represents a foundational life skill that directly shapes domestic stability, reduces marital stress, and dictates the generational wealth passed down to children. Developing a collective, household-wide financial acumen ensures that money acts as a tool for long-term security rather than a source of persistent anxiety.
The Foundation: Modern Budgeting and Cash Flow Management
Every resilient household financial strategy begins with transparent cash flow tracking. Without an accurate understanding of what enters and leaves the home each month, creating savings goals or paying down liabilities becomes impossible.
Modern budgeting moves away from rigid, punitive models and focuses on value-based allocation systems. Families thrive when they understand the functional distinction between fixed survival obligations, long-term wealth building, and lifestyle flexibility.
-
The 50-30-20 Baseline: A balanced starting structure allocates fifty percent of take-home income to essential needs like housing, groceries, utilities, and insurance; thirty percent toward discretionary lifestyle expenses; and twenty percent directly to debt reduction and automated savings.
-
Zero-Based Allocation: For families needing tighter controls, assigning every earned dollar a specific job before the month starts eliminates mindless financial drift.
-
Subscription Audits: Digital subscriptions create invisible spending leaks. Reviewing bank statements every quarter to cancel unused streaming platforms, app memberships, and software trials can free up significant monthly capital.
Taming Modern Consumer Debt and Credit Optimization
Credit cards and modern lending products offer convenience, travel perks, and purchase protection. However, when misunderstood or mismanaged, compounding high-interest debt rapidly destabilizes household security.
Financial literacy requires every adult in the household to understand how the credit ecosystem functions.
-
Credit Utilization Ratios: Credit scoring models heavily weigh how much available revolving credit a family uses. Keeping total balances below thirty percent of maximum limits preserves a healthy credit rating, which directly reduces interest rates on future home mortgages or auto loans.
-
Strategic Repayment Frameworks: Families carrying multiple liabilities must choose between the debt avalanche method, which prioritizes accounts with the highest interest rates to save total money, and the debt snowball method, which clears the smallest balances first to build psychological momentum.
-
Understanding Buy-Now-Pay-Later Pitfalls: Installment loan programs embedded in online checkouts break purchases into smaller chunks, masking the true cost of consumer goods and encouraging overextension. Treating these transactions with the same discipline as traditional credit cards prevents unexpected accumulation of micro-debts.
Building Resilient Safety Nets: Emergency Funds and Insurance
Financial setbacks are not a matter of if, but when. Job disruptions, medical emergencies, home repairs, or vehicular breakdowns are routine events over the course of family life. A household without an emergency buffer often turns to high-interest personal loans or credit lines, triggering a destructive debt spiral.
A comprehensive emergency reserve serves as the family’s balance sheet armor.
-
Determining the Ideal Reserve: Single-income households or self-employed parents should maintain six to nine months of baseline living expenses in a dedicated account. Dual-income households with stable employment can typically operate safely with three to six months of expenses.
-
High-Yield Savings Accounts: Emergency cash should not sit in a zero-interest checking account. Placing these funds into a high-yield savings account or money market account provides liquidity while earning meaningful yield to offset inflation.
-
Risk Mitigation Through Insurance: True financial planning protects against catastrophic loss. Families require adequate term life insurance for primary income earners, disability insurance to replace income in case of illness or injury, and comprehensive umbrella liability coverage once household assets grow.
Age-Appropriate Financial Education for Children
Children learn about money far more from observing parental habits than from formal school lectures. In a society where physical cash is increasingly rare, parents must find intentional ways to make digital money tangible and understandable for the next generation.
Integrating financial literacy into different stages of childhood ensures that kids develop healthy spending instincts and understand the value of labor.
-
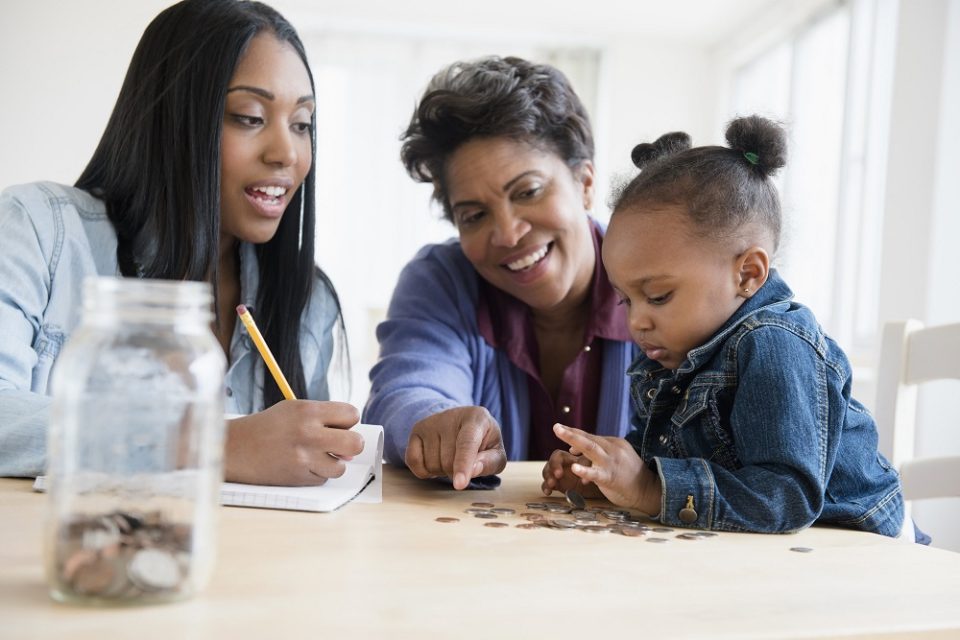
Early Childhood (Ages 4 to 8): Introduce physical coins and clear jars labeled for spending, saving, and giving. Seeing physical coins accumulate creates a concrete visual connection between patience and rewards.
-
Pre-Teens (Ages 9 to 12): Transition to digital literacy by introducing managed debit cards with parent-controlled limits. Tie allowances to household contributions rather than entitlement, and teach the basic mechanics of comparing unit prices at the grocery store.
-
Teenagers (Ages 13 to 18): Involve teens in real-world discussions about auto insurance costs, cell phone plans, and college tuition. Guide them through opening a high school checking account, filing their first income tax return from summer jobs, and opening a custodial Roth IRA to introduce compounding growth early.
Long-Term Wealth Creation: Investing and Estate Planning
Saving money in cash reserves protects against short-term volatility, but investing in appreciating assets builds multi-generational freedom. Inflation continuously erodes the purchasing power of idle cash. Families must harness compound returns through structured, low-cost investment vehicles.
-
Tax-Advantaged Retirement Vehicles: Maximizing contributions to employer-sponsored 401k plans, especially up to the company match limit, is an immediate return on investment. Supplementing these with traditional or Roth IRAs provides tax diversification for future distributions.
-
College Savings Vehicles: Utilizing 529 College Savings Plans allows parents to invest post-tax dollars that grow tax-free and withdraw without penalty when spent on qualified education expenses.
-
Foundational Estate Documents: Estate planning is not exclusive to the wealthy. Every modern family with minor children needs a basic will to designate legal guardians, a healthcare directive, and durable power of attorney documents to protect the family if an adult becomes incapacitated.
Fostering Transparent Domestic Communication
The final pillar of family financial literacy is psychological and interpersonal. Money remains one of the leading causes of domestic tension and divorce. Silence, shame, or unilateral financial decision-making creates resentment.
Scheduling monthly, low-stress financial check-ins allows partners to review bank accounts, celebrate milestone achievements, and recalibrate spending priorities together. When parents speak openly, constructively, and objectively about money, they strip away the taboo and cultivate a household environment centered on teamwork, security, and long-term prosperity.
Frequently Asked Questions
How should parents manage an allowance for children effectively?
An effective allowance system balances basic household participation with opportunities to earn through extra initiative. Basic personal responsibilities, such as cleaning one’s room or clearing the dinner table, should be unpaid baseline contributions to the household. Parents can then offer optional, labor-intensive tasks like washing family vehicles, yard cleanup, or garage organizing to teach children that discretionary money is earned through focused effort and delivered value.
What is the ideal way to divide financial responsibilities between partners with unequal incomes?
Many modern couples find success using a proportional contribution model. Instead of splitting household bills down the middle, each partner contributes a percentage of their personal income toward shared joint expenses. For example, if one partner earns seventy percent of total household income and the other earns thirty percent, they fund the joint living account in that exact 70/30 proportion, leaving both individuals with fair discretionary money for personal savings.
How does an individual determine whether to pay off debt or invest extra income?
The decision hinges primarily on the guaranteed interest rate of the debt compared to the expected after-tax return of investments. High-interest unsecured debt, such as credit card balances carrying fifteen to twenty-five percent interest, should be paid off aggressively, as no standard investment reliably beats that guaranteed cost. Low-interest fixed debt, such as a low-rate mortgage below four percent, allows more room to balance repayments while investing extra capital into broad-market index funds.
What steps protect a family against identity theft and digital financial fraud?
Families should freeze their credit files with all three major credit reporting agencies, preventing unauthorized accounts from being opened in their names. Additionally, deploying unique, complex passwords via a dedicated password manager, enabling hardware-based or app-based two-factor authentication on all banking portals, and regularly monitoring credit reports eliminates common cyber vulnerabilities.
What is the key difference between a custodial account and a trust for a minor child?
A standard custodial account under the Uniform Transfers to Minors Act transfers full legal control of all assets directly to the child once they reach the state age of majority, usually eighteen or twenty-one, regardless of their financial maturity. A legal trust allows parents to establish specific milestones, rules, and timelines dictating exactly when and how distributed assets can be used, such as funding higher education or buying a first home.
How can a family start investing with very small amounts of money?
Modern brokerage firms offer zero-commission trading and fractional share purchases, allowing families to invest with as little as five or ten dollars. Setting up automatic monthly transfers into low-cost broad-market index funds or exchange-traded funds removes the barrier to entry and automates the wealth-building habit without requiring large initial lump sums.
How should a family prepare for major future economic shifts or inflation?
Preparing for economic volatility requires maintaining low fixed recurring overhead, avoiding variable-rate consumer debt, diversifying income streams where feasible, and investing in tangible, cash-flowing assets or broad equities that naturally adjust their pricing alongside general inflation trends. Keeping liquid emergency funds healthy also provides the breathing room needed to absorb temporary cost-of-living spikes.